
It’s time for yet another spring property market update with the wonderful Kellie Landrey – principal Buyer’s Agent at Scoutable – whose down to earth approach to property buying and accessible, relatable market insights always leave us feeling better informed.
KEY INSIGHTS:
- The market has pulled back, but it’s not in free fall: Kellie estimates a pullback of around 10% across price ranges in her patch, with the $3M-plus end more impacted than $1.5M and under.
- Competition has dropped right off: There are now one to two buyers on a property, compared with five to eight last year – even though inspection numbers are picking back up.
- Stock is still tight: Local agents are reporting stock levels down around 30% on last year, and auction clearance rates are sitting around 50% (compared with around 80% last spring).
- First home buyers are facing less competition: With investor activity down in the $1.5M and under bracket, first home buyers are facing less competition and getting deals together.
- Investors are holding back: The budget changes have hit investors hardest, while the rate rises have weighed more on owner occupiers.
- Upgraders, this could be your moment: Moving up from the $1M–$1.5M market into the $2M–$2.5M market is a real opportunity right now.
- Value properties on the last 12 weeks of sales: Anything older than that needs a discount applied.
READ TIME:
Approx. 12 - 15 mins
JUMP TO:
Section 1: Spring Market Conditions ↗︎
Section 2: Rate Rises, Budget Changes & Government Schemes ↗︎
Section 1: Spring Market Conditions
Pure Finance: Hey Kellie, we can’t believe spring has come round again so fast! We’re not sure about you, but if we had tried to make predictions a year ago on what we think the market would look like for spring 2026, we’re not sure we would’ve been able to predict what’s happened so far this year. From 3 rate rises (rather than the promised further rate cuts), to the federal government’s budget announcement to changes to negative gearing and capital gains tax (CGT), it’s already been a year. So, we feel it’s never been more important to chat with our resident expert (you), to hear about what the market is up to.
To start off, what is the vibe you’re noticing in the market right now?
Kellie Landrey: Well it’s definitely a different conversation from this time last year – all the things you just mentioned have really impacted the market. From my end, we actually started to see the market retract at the beginning of the year.
PF: So, before the budget changes?
KL: Yes – with everything going on in the world in general, we were already seeing some hesitation and some slowdown in the market in the first and second quarter. Then the rumours of what the budget was going to be, and then the budget itself, all combined and really started impacting the market.
A lot of the agents I spoke to around the end of April and beginning of May were losing listings, because people were saying, ‘no, we just want to wait and see what the market’s doing, we don’t want to sell right now’. So, stock levels started to pull back even before anything got implemented. And as soon as the budget came into effect, it was sort of the nail in the coffin of what was already happening.
From May until July, there weren’t a lot of transactions happening across various price points. Now, some confidence has returned, and the budget is somewhat of a distant memory for some buyers. But people are only really selling if they have to – no one’s doing an opportunistic sale to upgrade or downgrade unless they need to.
So, stock levels are still low. I’m talking about my patch really – the inner 10km radius of Sydney or Melbourne – but this is being felt across different markets around Australia in some capacity. What I’m seeing is that the market has pulled back about 10% across the price ranges, and it’s more impacted at the top end than the bottom end.
PF: Sorry, just to clarify – more impacted at the top end than the bottom end?
KL: Yes so, when I say that, I mean $3M-plus is more impacted than $1.5M and below. That’s because serviceability, affordability, first home buyer incentives and so forth are holding the $1.5M and under market better than the upper end.
So at the moment, if you’ve already bought a property somewhere in the $1M–$1.5M market and you’re ready to take the next step to $2M–$2.5M+, this is your time. It’s the most amazing opportunity to sell, for example, your two-bedroom apartment and upgrade to a three-bedroom terrace or house. I know not all buyers are in the inner city, but if that’s where you are right now, these are dream conditions for you. So it’s not all doom and gloom. If you’ve got confidence in your personal situation, there are some positive buying opportunities out there.
PF: And how’s that playing out at inspections and auctions?
KL: In my experience, where last year there might have been five to eight buyers on a property, there’s now one to two. So, the competition has pulled back completely. That doesn’t mean properties are going for ‘a bargain’. If a property is ticking all the boxes, it’s still selling reasonably okay – it’s just not going for a premium price. And, like normal, the properties with something not quite right (the street, the condition, whatever it may be) are feeling the full impact of the downturn and aren’t really trading well.
What I have noticed in the last few weeks, in particular, is a lot more people inspecting properties. A month ago, it wouldn’t be uncommon for it to be just me and one or two others at an inspection. Now there could be twenty to thirty people. But there are still only one or two buyers actually wanting to buy the property – that hasn’t changed.
PF: Are you seeing anything on the ground right now that differs from what the headlines are saying?
Interestingly, the Guardian recently reported that pre-approval numbers from the banks really dropped back from May to July, then picked up quite a lot in the first two weeks of August. It sounds like you’re seeing something similar?
KL: Yeah, people are more curious, but it’s not really changing the competition yet – though I think that will potentially flow on. The difference between the headlines and reality is that it’s not completely dire. Yes, there is a correction going on, from the impact of all the things we know are happening. But we’re not in free fall, with properties going drastically low. It’s not as drastic as the media is making out. And for me, I feel like the media drives the property market more than the actual facts of the market.
Let’s say the cash rate remains on hold at the next meeting, and stock levels don’t come into any greatness in spring (which I think is a possibility). If the media then starts writing, ‘stock levels are down, cash rates on hold, the economy is improving’ and those become the new headlines, that’ll turn the market – even though nothing has necessarily fundamentally changed.
PF: That makes sense. After the budget, it felt like every Monday there’d be an article about how terrible the auction results were, and it was just feeding this negative spiral about how the market had completely turned.
KL: Yeah, from the Cotality data for August, Sydney was down 4.7% over the quarter and 4.6% annually with Melbourne down 3.9% for the quarter and 4.7% annually. I know we’ve spoken about this before with regards to Melbourne not performing as strongly as other cities, but it had started to recover at the end of last year.
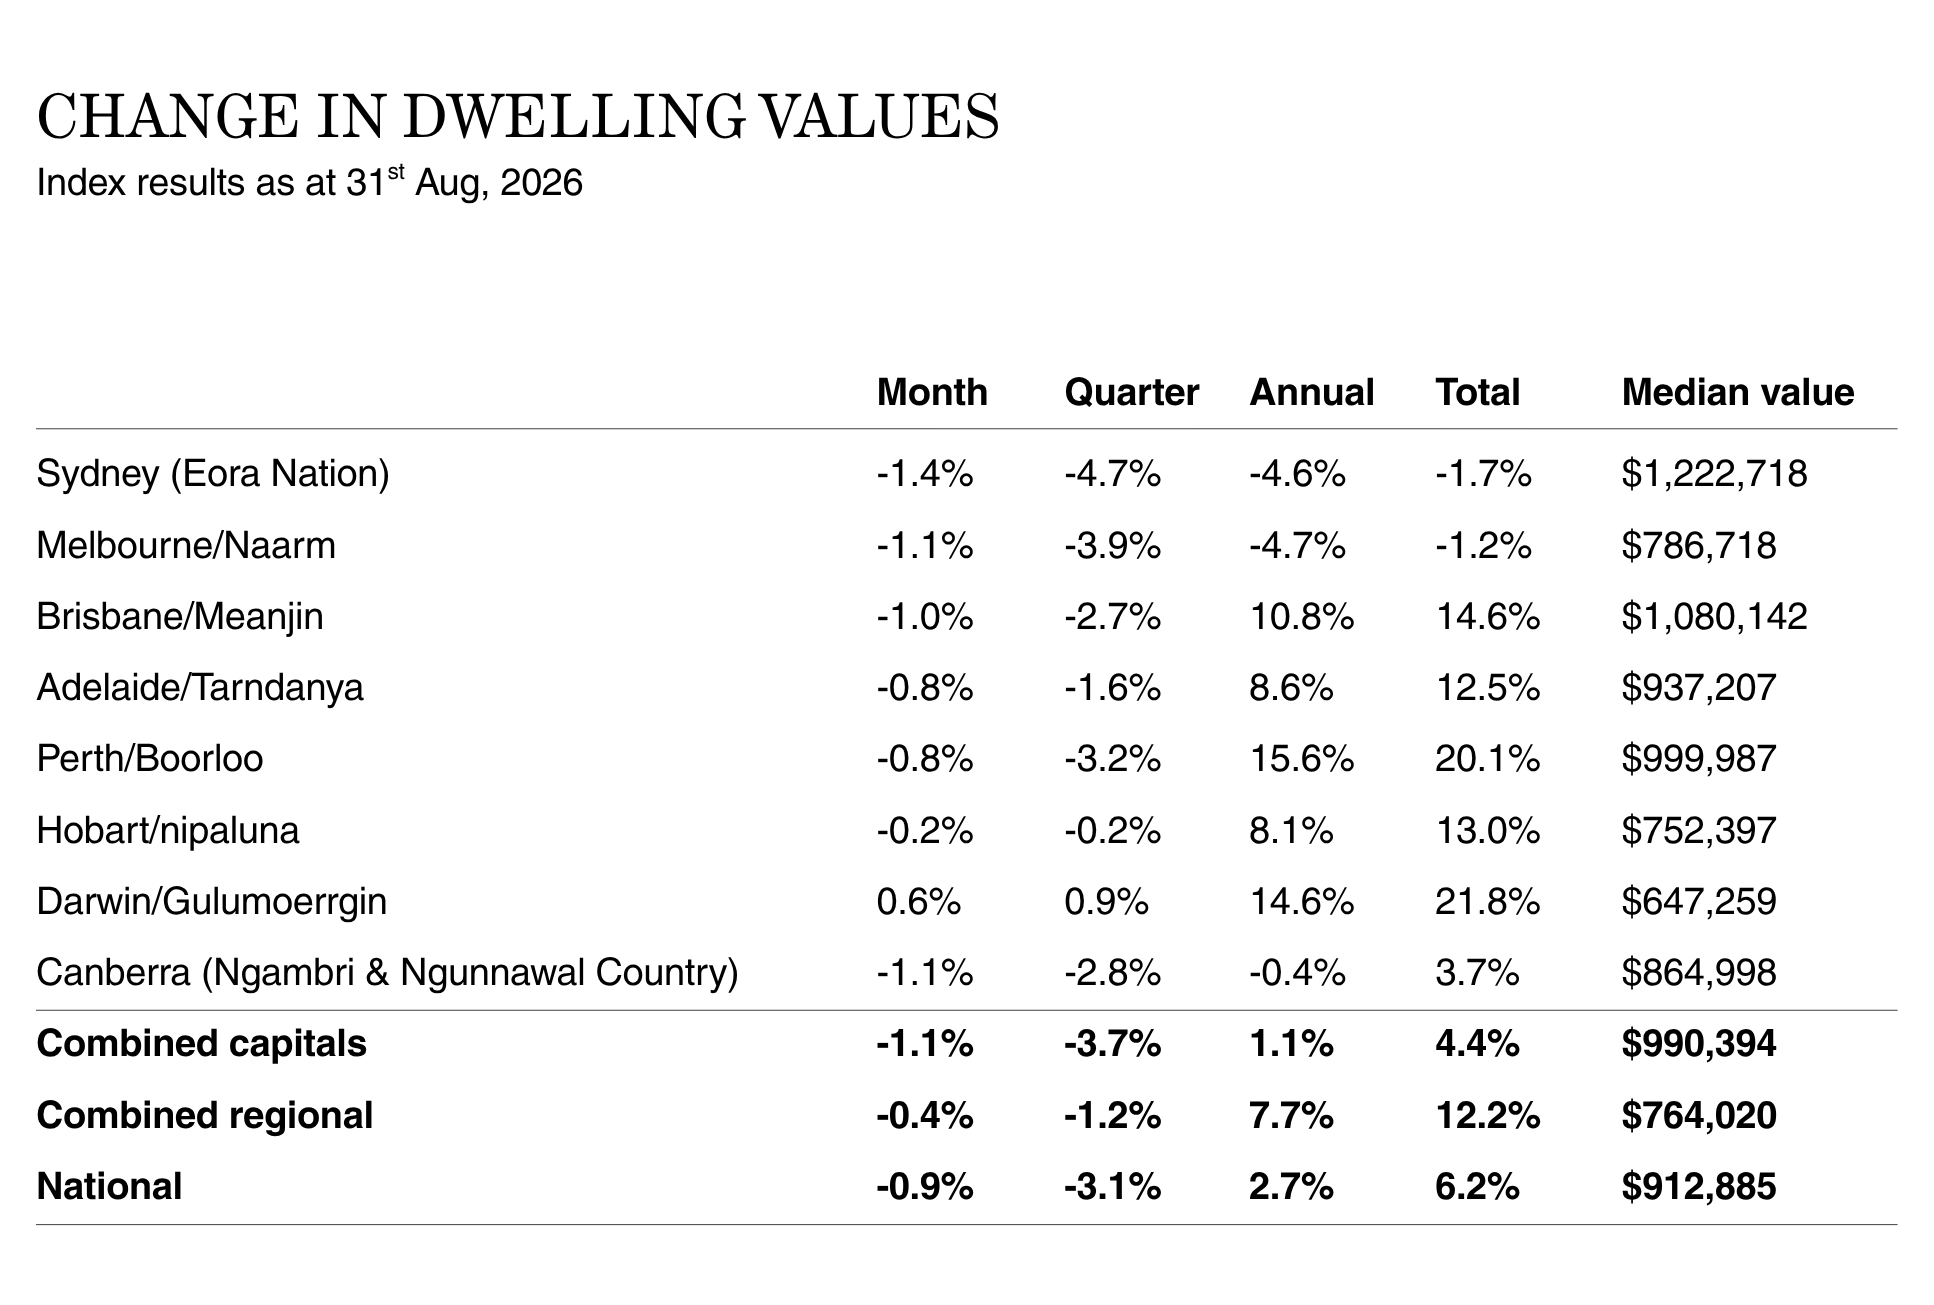
But what I’m saying is, these numbers aren’t drastic. Yes, it’s impactful because we’ve been in a rising market for so long, but we still have enough equity and growth since COVID and since the last peak. Looking back now, it seems October last year is when we started to shift from being a rising market to more of a correction.
Also, these figures are averages, and different suburbs perform differently. People who bought a year ago are probably more impacted, but people who have held property for five-plus years are still okay. Over a 10 or 15 year property cycle, there will always be ups and downs that balance out, and your home or investment will still have performed relatively well compared to other asset classes.
So, we’re just in a period of correction driven by things outside the market’s control – both global events and internal things that are going on. I think we’re going to be in a low growth environment for a little while – I don’t think we’ll see accelerated 10% or 15% annual growth – but I don’t think we’ll keep going backwards either. I read an article the other day, I think by Cotality, that said it’s possible (pending cash rate movements) we’ll look back and find that this was the bottom.
Melbourne is a bit different – it hasn’t really had any growth at all since COVID, whereas every other market has performed. Some people would look at Melbourne and say, “That’s what should have been happening, because we’re trying to make property more affordable and slow the growth down”.
PF: I’d say we’d agree. And we think this represents a good opportunity for buyers.
KL: It depends what kind of wealth creation you’re trying to do with the property, and how you view it.
“I feel like the media can drive the property market more than the actual facts of the market.”
PF: What sort of feedback are you getting from buyers and sellers at the moment, based on the properties that are or aren’t selling?
KL: At all the auctions I’ve gone to over the last month, I’ve more or less been either the only bidder, or it’s been me and one other bidder. Pretty much every time, the property has passed in – either to me or the other buyer – and then negotiations have failed. Then it goes up for sale, and might sell a few weeks later once the vendor comes in line, or the property gets re-rented.
There are a lot of sellers still holding onto the price they want, which is a price from three months ago. If they don’t have to sell, or they change their mind about selling, they’re really not negotiating. Then there are sellers who have already bought and need to sell (on long settlements and things like that). They’re the ones feeling the pressure, and they’re selling for less.
So sellers are sort of in two camps: they’ll either take what they get, or they’ll hold firm and the property will hang on the market. I’m also finding there are lots of off-market properties which are overpriced.
PF: So, seeing as though it looks like we're in the middle of a bit of a correction, how do you expect the 2026 spring season to differ from previous years?
KL: What I’m finding on the ground, as opposed to what the data is telling us (because the data always lags behind), is that local agents are probably down about 30% on last year’s stock levels. Ordinarily, they’d have a big burst of properties coming onto the market this month – it’s one of their prime months. But agents across a broad spectrum of areas and price points in Sydney are all telling me pretty much the same thing. The data is saying Sydney is 6% above the five-year average for stock levels, but I’m feeling like it’s much, much less than that.
So it would appear stock levels will remain relatively low this spring compared to previous years, because people are only selling if they need to. Don’t be surprised if you see lots of people at inspections, because that’s what’s been happening over the last fortnight. But I’m not feeling an auction environment where multiple people are bidding on a property. So I think buyers have more ability to negotiate now than in previous seasons.
The other thing – and this is something you can check without looking at the headlines – is the auction clearance rate, which I think will probably stay relatively low. At the moment it’s around 50% on average, compared with about 80% last spring. A low clearance rate means there’s a mismatch between vendors’ and buyers’ expectations. When clearance rates are close to 100%, sellers are in charge; when they’re really low, buyers are in charge.
PF: We’d add one more indicator: when you start getting random calls and emails from real estate agents asking if you’re ‘still looking’...
KL: Yeah, when they start chasing you! As buyers and sellers come closer to each other’s expectations through spring, I think clearance rates could improve to around the 60% mark. But generally speaking, I think the averages will sit around where they are – though brilliant properties will always be competitive.
I think you’ll find that what’s missing from the spring market at the moment is FOMO. And that takes the urgency out of it.
“If you’ve already bought a property somewhere in the $1M–$1.5M market and you’re ready to take the next step to $2M–$2.5M+, this is your time.”
Section 2: Rate Rises, Budget Changes & Government Schemes
PF: How are the recent rate rises (in February, March and May) influencing buyer decisions and market activity vs the federal government budget changes? Do you think one has had more of an impact than the other, or that they’re both having a similar impact?
KL: It’s pretty hard to say, because they’ve compounded on each other. The interest rate movements definitely had an impact as they were happening, changing the confidence of the market and causing hesitation from both sellers and buyers alike. Then the budget created more significant uncertainty, particularly in the investor market, because the changes had a much bigger impact on investors than on owner occupiers.
The instant reaction was, ‘what should I do now? How should I approach this? Should I be buying in a trust or in my own name? Should I be buying a new build or an established property?’ So, conversations needed to take place with the team around the buyer, like accountants and financial advisors – who were also trying to work out the best structure. A lot of pausing happened in that period, because people were trying to figure out how they should own a property. Then taking lending out of super also had an impact.
So, I’d say the budget impacted the investor market more significantly than inflation or rising interest rates. But for owner occupiers, it’s been more the interest rate movements than the budget. Because while owner occupiers’ serviceability is impacted by the interest rate movements, the budget is making them feel like they have more power to buy.
PF: And what about sellers?
KL: Again, it depends – it does have some correlation to the ownership structure, i.e. whether they’re an investor or an owner occupier. In the budget announcements, negative gearing was grandfathered. So if an investor was thinking about selling to go and buy another investment, they paused that consideration, because if they sold, they would lose that benefit. So there are investors out there who maybe were considering selling who are no longer selling.
I’ve had various conversations along the lines of, ‘I really need to consider what I’m selling this property for, because I want to hold on to the benefits I currently have’. Serviceability has also been impacted by the loss of negative gearing, which comes into play when they think about growing their portfolio.
Then there are owner occupiers. People selling are usually selling to purchase, using that equity to go and do something else with it. I’m finding there are sellers who are no longer selling, because they’re happy with their current environment and don’t want to be put into the new order. Owner occupiers are really only selling if there’s a life event causing them to sell. If they were on the fence about the decision, they’re just not selling – and that’s probably equally a combination of interest rate movements and the budget. It’s just how the market performs when there’s more than one isolated event going on.
PF: Last year we had the broadening of the eligibility for the 5% deposit scheme for first home buyers right in the middle of the spring season. Then, before the end of the year, the Help to Buy scheme finally became available. There’s been a lot of chatter that both of these schemes have helped prices to keep rising for properties priced under the scheme cap. What have you noticed?
KL: When it first came into effect, I noticed there was definitely a race to $1.5M for certain properties [the scheme’s price cap in Sydney, where Kellie predominantly works]. And as soon as a property went over $1.5M, a lot of those buyers just couldn’t or wouldn’t buy it. So at the time, for my investor clients, second home buyers or people who didn’t have access to the scheme, we would offer $1.505M. That meant that instead of six or seven people competing up to $1.5M, there was just us or maybe one other party offering over $1.5M. So for $5,000–$10,000, a bunch of people just disappeared from the competition.
PF: Kind of like a scheme ‘cliff’ if you will?
KL: Yes, completely. In more recent times, I do think the schemes and the stamp duty concessions (despite their differing caps) have definitely kept that market turning over, by helping some people get into those marketplaces. Those markets still have hesitation for the various reasons we’ve discussed, but the schemes have kept the competition there.
“For $5,000–$10,000, a bunch of people just disappeared from the competition.”
PF: Similarly, with the federal government’s changes to negative gearing and CGT, there’s been reports of investors leaving the market (almost en masse). Are they stepping back or not? And how is investor activity affecting other buyers/the market?
KL: Yeah, I’d say that investors are not completely gone from the market, but they’re definitely holding back. Just from my own client portfolio, I probably have about 80% fewer investors on my books than I did at the beginning of the year. I have mainly owner occupiers looking. I still have investors coming in to chat, but they’re not necessarily actioning it. And other buyer’s agents I know, who mainly focus on investors, don’t really have much work on at all, if any.
I think investors are considering, restructuring, and talking to their financial planners or mortgage brokers or whoever.They’re having those conversations about what it looks like for them to invest in established residential properties moving forward.
PF: What are the main reasons they’re holding back?
KL: One, their serviceability has changed – you guys will know this more than anyone. Negative gearing benefits are no longer added into their serviceability calculation, so that’s impacted what they can and can’t buy.
People also don’t really understand that, whilst you can’t negatively gear on an annual basis, it still accrues and builds over time. But people do need to be able to cover that shortfall on an annual basis, without getting the refund in their tax return – which some investors, especially rentvestors, really rely on to help them get into the market.
I think that’s one of the pitfalls of this budget. A lot of first-time buyers I’ve worked with over the last 10 years really did use negative gearing to help them get into the market and eventually move into that property. Now that option has sort of disappeared for them, because they can’t afford to do that anymore. So that’s a bit of a negative (pun intended), or a bit of a side effect.
My personal opinion is that I’m fine with them wanting to change the rules around it, but they should have really considered allowing individuals to hold one property that you can negatively gear. Stop people owning 30 properties – fine, if that’s what you want to do. But people should have been able to have one, or maybe even two, because it helps them create wealth and get into the market.
PF: Yes, we’d tend to agree with that. And is that the link to there being less competition, as you were saying?
KL: Yes and no. If you’re at, say, the $2.5M–$5.5M price point, there’s probably more weight to owner occupiers in that space anyway, and that’s been really impacted by the market downturn. In the $1.5M and under bracket, where you’d find more investor activity, that’s gone. But as I said, there are more incentives around for owner occupiers, so they do have less competition and they are getting deals together. There are still more first-time buyers in the market than there are second or third-time buyers in the other price points. So it has taken some competition out, but I don’t think it’s what’s driving the market.
Section 3: Buyer Strategies & Opportunities
PF: What would you say to potential buyers who might be waiting for the ‘right time’ to buy in 2026?
KL: Everyone always says this, and it’s common because it’s true – I know I’ve said it to you guys before – but it really is impossible to time the market in this way. What I find most people do in a market like this is say, ‘I’m going to wait, because I don’t think it’s fallen enough yet’. But if you’re sitting on the fence waiting for the bottom to happen before you buy, just know that nobody knows it’s the bottom until it starts to rise. So if you’re waiting for that to happen, it means the market’s already moved.
The question you need to ask yourself is more about your personal circumstances. Get your finance pre-approved. Do all your research. Then, if the property is within your budget, the repayments are within your means (factoring in whatever buffer you need to feel comfortable), and you can get the property for what feels like a good price, that’s what you should be buying.
And there’s something I think is really important for buyers right now, because of the way the market has moved in recent times. When you’re trying to figure out what a property is worth, you really need to focus on only the last 12 weeks of sales. If a sale is older than 12 weeks, you need to apply a discount to that price to work out what you should be paying now. That’s because things are changing almost on a monthly basis.
But that’s not completely shutting your mind off to what the market’s doing when you’re working out how much to pay. You still need to reflect on what has recently sold. I wouldn’t go back a year and say, “that sold for $1.5M a year ago, they’re asking $1.5M for a very similar product, so I’ll just pay $1.5M”. That shouldn’t be your mindset. Don’t ignore the market, but don’t make ‘timing the market’ the prime focus of your journey.
“When you’re trying to figure out what a property is worth, you really need to focus on only the last 12 weeks of sales.”
PF: Where do you think buyers can still find genuine value right now – whether that’s a particular market segment, suburb, property type or price bracket?
KL: Like I mentioned earlier, if you happen to be in that $2M–$4M price point, there are really good opportunities there. But there are good opportunities across the spectrum of the market. So wherever you are looking, and whatever you are looking for, there are opportunities out there for you to buy at a decent price right now, compared to six or twelve months ago.
PF: Interestingly, some of the first-time buyers we work with who were weighing up buying a home vs rentvesting have decided to buy a home, primarily because of the negative gearing changes. And some people who recently bought their first home have reached out to run the numbers on an investment property, thinking now might be a great time while people are getting scared off.
KL: Yeah, I’m also having conversations with people in a similar scenario, about turning the home they’ve just bought into an investment property and buying another home to live in, so they can have negative gearing on that first property.
But negative gearing isn’t the be-all and end-all. It helps facilitate the management of your cash flow, but you still have to pay the money – you’re just getting it back on an annual basis, as opposed to in the future. So obviously it impacts how much somebody can pay currently. And serviceability is decreasing because of the removal of negative gearing for most purchases.
It just means that investors who would have bought a property for $1.5M might now be focusing more on a $1M–$1.2M property. But what you’ll find is that, even though the government said this isn’t going to happen, rents have actually increased, and will continue to increase if rental stock continues to decrease. And as yields improve, that does attract more investors to the market.
But in high quality, A-grade growth locations, you’ll never have a cash flow positive property at an 80% LVR. You can buy positively geared properties – it’s possible – but they’re not in the dominant owner occupier markets where you see the most growth in an asset. So there will still be some sort of shortfall that needs to be compensated for, especially in Sydney, because our yields are low. Right now, and for the next 12 months, I can’t see a big flow of investors, but it will improve over time.
PF: Are you seeing any significant shifts in the way properties are selling at the moment?
KL: Properties are still being sold via an auction campaign, because the purpose of the auction campaign is to create urgency for buyers, as opposed to putting it on a ‘for sale’ price. But what I’ve noticed in Sydney is that half the properties are actually not selling on the floor on auction day – they’re either selling before or, more likely, after. Melbourne is similar, but there are more private treaty sales in Melbourne than in Sydney.
The reason they’re not selling before as much is because the vendor needs to see the process play out to realign with the market price. So say the reserve is $1.5M or $3M, but the property is only getting to $1.2M or $2.7M – it’s falling short of the reserve. They try to negotiate on the day, it more than likely fails, and then they’re just doing it after.
Just last month, I was bidding on a property in Glebe and we were the highest bidder. It passed in, and it’s still for sale now.
PF: What? And they didn’t want to accept the price?
KL: Yeah. It’s a beautiful terrace that would have ordinarily flown out the door, but the vendor has the wrong price in their mind, and they’re in a situation where they don’t need to sell. Whereas if that vendor had already purchased, they probably would have taken our offer.
Where the vendor is aligned with the market, properties will still sell pre-auction, because they just get the sale done.
One thing I am noticing in particular is that most selling agents are saying to me that the ‘right’ buyer is engaging within the first two weeks of the campaign. So it’s more about the selling agent – not convincing, but sort of educating the seller that ‘this is your buyer, this is the price’, and that if they don’t take it, the buyer will probably move on to something else. Because there aren’t five or six buyers on a property right now, agents are trying to engage with whoever they think is the right buyer as soon as possible. But the vendors are not always listening to that conversation.
“Most selling agents are saying to me that the ‘right’ buyer is engaging within the first two weeks of the campaign.”
Section 4: Practical Tips & Advice For Buyers
PF: What are some of the common pitfalls you’re seeing buyers run into in this market? (Not having a pre-approval is always on our list!)
KL: Waiting for the ‘right’ time. And if buyers are into a property but exploring other options before they make their decision, the one they really like might sell – especially if that situation I just explained happens, and they haven’t done their research.
Obviously, when properties aren’t flying out the door, people feel relaxed. So if you really do like a property, you don’t have to be aggressive to get it, but just make sure you’re ready to go as well. It’s understandable that buyers have uncertainty, because it’s definitely a different market to what we’ve experienced in recent years. So just do your research, be comfortable, be ready and be confident that you’re making the right decision for you.
PF: Totally agree. Any other tips for people hoping to buy in 2026?
KL: Just the normal things. To give yourself confidence, have a little buffer – for interest rate rises, if that were to happen, and for any maintenance, things like that – so you can go in with confidence with the budget you’re setting yourself.
Always remember to look at neighbouring suburbs to the one you love the most. If you cast a little bit of a wider net, you might find some better opportunities, or maybe even less competition. Sometimes you might be able to get yourself a significantly better property just by going a kilometre down the road.
Research. Inspect lots. Take your time, but don’t dilly-dally if you really like it. I don’t want anyone to freak out and think they have to buy straight away, because they don’t. But I find that most buyers will spend a lot of time making an informed decision, and then listen to a bunch of people in their circle – be it parents, grandparents, friends, couch property experts – who put the fear of God in them. And then they talk themselves out of buying the property.
So, like I said before, just try and quieten some of the noise. I always find that writing down your top 10 preferences for the property is helpful. Refer to it, make a little table, and tick off what the property achieves. If it’s achieving 8 out of 10 things on your wish list, and you can afford it, and you feel good about it, then that might be the one.
“If it’s achieving 8 out of 10 things on your wish list, and you can afford it, and you feel good about it, then that might be the one.”
PF: And, as always, the questions on everyone’s lips: what are your predictions for this year’s Spring buying season and/or the rest of the year? (Taken with a grain of salt, as always.)
KL: Obviously, like with what you’ve seen over the last six months, what happens with inflation and cash rates over the remainder of the year is going to have an impact on how the market actually flows.
PF: And right now, there’s a big question mark over all of that.
KL: Yeah, so it could go one of two ways. I don’t think we’re going to have significantly more reduction in value. Pending cash rates, inflation and stock levels, I think it’s potentially going to be somewhat similar to what we’re experiencing now. There might be a tiny little bit more of a dip over the remainder of the year – as in 1% or 2%, not 10%. If it is in a similar space to what we’re in now, I think the market has felt its correction and it’s just going to remain somewhat steady.
If the RBA raises the cash rate at the September meeting, then we can expect the market sentiment to be negative, buyers & sellers will likely be thinking ‘not again!’. The reaction to this is what we have already discussed; obviously mortgage repayments will go up and borrowing capacity will reduce. Buyer demand may soften more, and price growth could slow further in the coming months, especially at the higher end of the market and among investors.
So, If interest rates go up or stock levels go up significantly, then I think we’ll have more of a correction than if there is less stock and no cash rate movement. However, many buyers/sellers, and the market in general, already had some expectations this could be a possibility, and there’s a chance the market has already built in this scenario. It just really depends on what happens.
PF: And if a rate cut were to somehow materialise…
KL: That would change the market again. But I’m predicting – taken with a grain of salt, of course – that it’s very likely we’re going to be in a similar condition to what we’re in right now for the next six months.
There’s some hesitation from buyers and sellers across the board, but people are still buying and selling, and we’re not faced with drastic competition to buy an average property. It’s just going to be sort of steady as she goes. Unless something big happens that really impacts the market, I can’t see it drastically changing from here on out. But, you know, we didn’t know this was going to happen either.
I think it would be unwise for anyone to predict exactly what’s going to happen with the market over the next six months. Like I’ve said to you before, pre-COVID we could’ve had this conversation and I would’ve told you exactly what was going to happen. But since COVID, all of the world and life events that have happened have caused the market to be somewhat unpredictable.
You’ve just got to focus on your employment situation, your affordability and so on – all that kind of stuff is really important. That, and having some sort of buffer (whatever that buffer looks like to you) for any uncertainty you feel, will make you feel more comfortable. Then work within those means, and you should be able to ride out any storms that we may or may not face.
PF: Some great advice to end on there.
Well Kellie, as always, a big thank you for sharing your expertise and insights – it’s certainly helped us, and we know it’ll help many others in our community.
KL: A pleasure, as always.
Looking for more support?
Whether you're considering your first home purchase or looking to refinance, having the right support can make all the difference. If you'd like to chat about your options or if you’ve got questions about navigating the upcoming spring market - we're here to help!
Get in touch: info@purefinance.com.au
The information provided in this article is general advice only, and doesn’t constitute personal investment and/or financial advice. You should always reach out to us, or seek personal financial advice, if you’d like to discuss your own needs.